Thinking about your first home in the Eastern Shore? Start with a practical comparison of the property, the complete ownership budget and the places you expect to use. This guide helps you turn a broad search into specific questions you can verify before deciding.
Start with the right questions
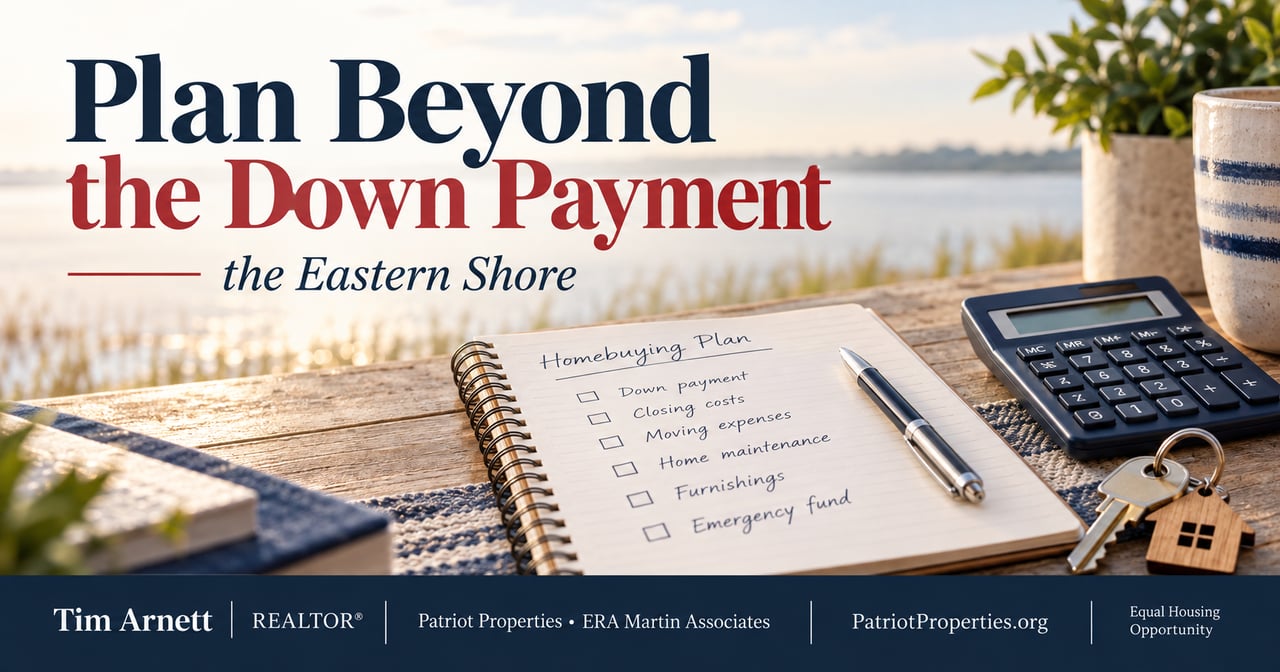
The cash needed for a first home is more than the down payment. Start with separate categories for the deposit, loan down payment, transaction costs, prepaid expenses and money you want to keep after settlement. The earnest money deposit is generally credited within the transaction rather than added a second time to the down payment. Its handling and refundability depend on the contract. Ask your agent and lender to explain the timing of every payment.
Investigate the details
Consider a hypothetical $300,000 purchase with a 5 percent down payment: the down payment alone is $15,000. This is arithmetic, not a loan offer or a current local median price. Settlement costs, prepaid insurance and escrow deposits would still need an address-specific estimate. A different loan may require different funds. Seller credits and assistance can change eligible expenses, but do not assume they cover every cost or replace all required buyer funds.
Apply the findings to your search
Keep the spending before and after settlement visible. Inspections, specialist evaluations, moving, utility setup and immediate repairs can affect your savings even if the mortgage looks comfortable. Decide how much cash you want left when you receive the keys. Ask for a lender worksheet that reconciles the deposit already paid, any credits and the final cash to close. This reduces the chance that an attractive down payment figure hides a difficult move-in budget.
Separate approval from affordability
A lender evaluates whether a proposed loan meets underwriting requirements. Your household budget answers a different question: whether the payment leaves room for ordinary spending and savings. Write down take-home income, recurring debt, transportation, utilities and other commitments before setting a housing ceiling. Keep settlement cash separate from money reserved for repairs. When an estimate changes, revisit the whole plan rather than adjusting only the purchase price. The right range supports ownership beyond the day the loan closes.
Compare like with like
Use consistent assumptions when comparing properties or financing options. Keep the down payment, loan term and occupancy plans clear, then identify differences in fees, insurance, taxes and recurring charges. Ask which numbers are confirmed and which are preliminary. If assistance or a seller credit is involved, verify its permitted use and any repayment conditions. A single advertised figure can hide tradeoffs. A written comparison makes it easier to understand where cash is needed and what affects the ongoing payment.
Frequently asked question
Can an online estimate decide my budget? It can help you explore assumptions, but replace those assumptions with a lender’s terms and address-specific costs before committing. Keep your own comfortable payment and post-settlement savings in the decision.
Your next step
I’m Tim Arnett, REALTOR® with ERA Martin Associates and Patriot Properties. If you are exploring the Eastern Shore, I can help organize a home search around your budget and priorities. Visit PatriotProperties.org to request a first-time-buyer conversation. If you already have an agent, continue coordinating your search with them.